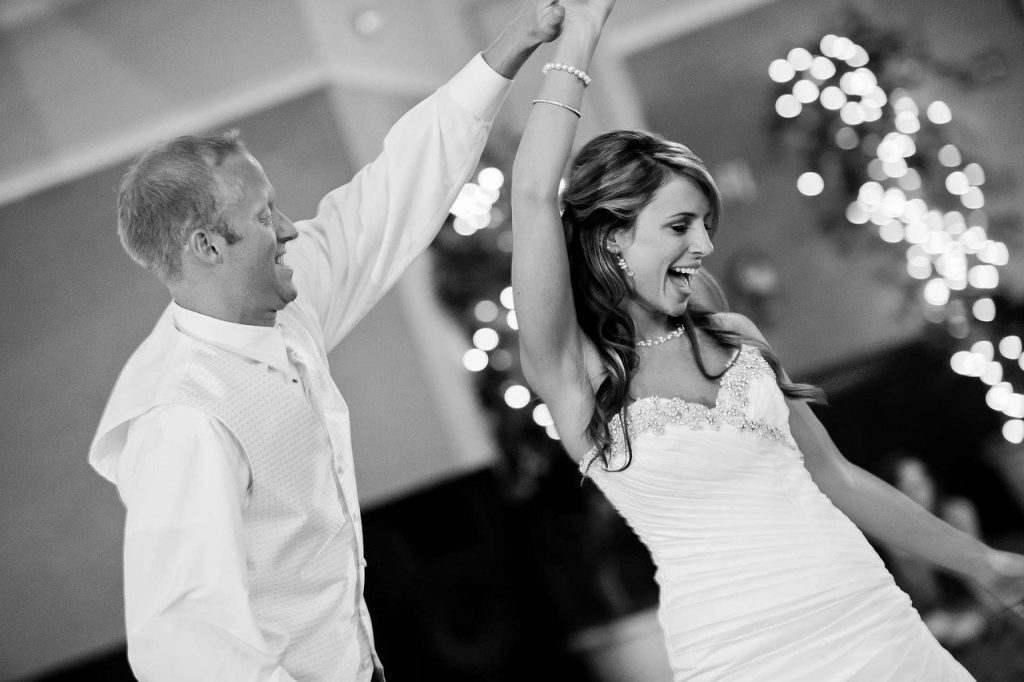
Wedding Dance

Surprise your guests Wedding dance choreography Calling all wedding couples, how would you like to dance your first dance to the music of your own choice have that special tune you both love, you know your song. Well let me choreograph your dance for you, not just a waltz or anything to fit in with the normal.

Your first dance is special. Your dance can be low key or as extravagant as you wish, if you desire you can also include your best man and bridemaids etc. All musical tastes catered for. Many years experience of teaching wedding couples, come and see sonia a trained choreographer in all music rhythmical styles.

Note for future bride grooms, fellows don’t panic its great fun, we havent had a failure yet! .

Anniversary, Engagement and Special Occassion Dances, Themed Events

Have you got a special anniversary, engagement or another special occasion in your life, suprise your family and friends, with a dance routine that will be remembered for a lifetime, easy step by step instruction, friendly atmosphere.

We cater for singles, couples, groups, your chosen music can be anything from comedy, Hip Hop, romantic, dirty dancing, ballroom, latin, salsa, rock n roll, lindy hop, jive, themed events a speciality, etc. Anything you wish for your party suprise, we have done it all romantic, low key, spectacular even bizzare, give Sonia a call.

Related Post

3 traps business owners fall into when choosing insurance3 traps business owners fall into when choosing insurance

Many small businesses rush to buy insurance policies because they think that doing so is an obligation or that they need the money to pay it. Unfortunately, many of these business owners fall into the traps that some insurance policies create. Here are three common pitfalls that you may encounter when choosing insurance policies.

It is natural for people to think about insurance in order to have protection for many different aspects of their lives. For instance, auto insurance to protect you from a collision on the way to work, home insurance to protect your house from damage and theft, and life insurance to provide for your family. Yet, behind these normal needs hide some dark secrets that could mislead non-experienced insurance takers.

Unsplash – CC0 License

Expensive premiums on your car insurance

Why do insurance companies always ask you to pay a very expensive premium for what they offer? Not every insurance company is the same; rather, each company has its own distinct customer base.

It is common for premiums to soar in the market place for no reason, but it is not always true that you are exactly the type of customer that insurers are looking for. Loyalty to an insurance company is only effective when you are precisely the type of customer they can care for. Otherwise, it can be a good idea to shop around for an insurer whose cover matches your needs and your budget.

Other factors that can influence your auto insurance premiums:

  • A sudden change of address, as some locations may be deemed less secure for car owners, and therefore, your insurance will increase premiums.

  • Adding your teenager to your insurance policy.

  • Increased mileage or cross-state travel.

  • History of insurance claims or accidents.

Ineffective home insurance cover

The main problem when it comes to finding the right insurance for your home is that you need to understand the potential risks that can threaten your property. Failure to understand those risks means that you could pay a lot for insurance cover that doesn’t actually protect you when you need it.

These problems are some of the most common things people report when they are attempting to find the best home insurance.

  • Not understanding which DIY work is policy authorized, and cause damage accidentally that is outside the scope of the policy.

  • High-value belongings are not covered by the home insurance.

  • They have been forced to delay home improvement works to keep the cost of the home insurance policy low.

  • They didn’t know that some events, such as natural disasters, required additional purchases for adequate protection.

Inadequate life insurance

In the event that you die, having a life insurance policy that covers all of the assets you own protects you. For businesses, it is crucial to have life insurance policies that will help you and your family pay bills if you die. But you may find it difficult to make the right decision when it comes to buying a policy:

  • Not knowing the difference between a whole life policy and a term life policy and how they affect your family.

  • Accidentally choosing an unnecessarily high amount of coverage, which means you pay high premiums, but your family may never need the full amount.

  • If you have standing debts, not altering the policy coverage to reflect that financial situation.

  • Thinking that life insurance is only for old people and postponing it.

Finding insurance coverage that suits your needs is tricky, because many business owners have a lot of assets that need to be protected, including their property, their income and the value of their vehicles. Experts such as the Engarde Financial Group in Pittsburg can provide dedicated insurance advice to help you find the right cover for all your needs.

ChildrenEvent Invitations -Sending OutBirthday CelebrationInvites With Thought and CareChildrenEvent Invitations -Sending OutBirthday CelebrationInvites With Thought and Care

Children Party Invitations can be testing when it concerns the mix and suit of colors as well as prints that are offered. You may believe that it is difficult to obtain them right but you will certainly discover that there are some things that you require to do in order to see to it that your invitations look fantastic. There needs to be something for https://www.bizbash.com/sponsored/article/21195440/innovative-video-invitations-in-the-covid-era everyone amongst these numerous combined style welcomes. Lots of people have actually tried as well as many have actually fallen short to cover as numerous age groups as possible with their invites.

There are lots of various ideas to cover as lots of age as possible with your invites. Among one of the most popular is the dual C word that includes the two numbers 1 and 2 with each other. This is a preferred children event invites phrasing concept and also can easily be done by hand or by printing on. This is one more choice that can easily be done without much trouble.

Another alternative that is prominent is the use of the kid`s birthday celebration cake or cupcakes. These can easily be made use of as the base for the children event invitations. If you have a Gigeo Instagram special cake that you intend to include on the invites, after that you can obtain the invites published with the cake design on the front and after that provide the different cakes that you have for the guests to choose from on the back. This will provide an concept of the various selections that they have as well as allow them to choose less complicated.
When it pertains to the kids party invites phrasing, you can have a good time with it. There is no set formula, yet if you take a few straightforward words that explain the motif of the party as well as utilize them in the invite you will have lots of enjoyable. The invite can likewise be themed around the tasks or video games that you are having for the birthday. For example, if you are having a treasure hunt for the youngster`s 3rd party, you could create on the invites that the finder of the treasure is: Miss Mama and also Miss Father, which they are looking for the adhering to things: a packed ape, a gold coin, a locket, a heart-shaped box, a pirate flag, a princess` round, as well as various other such things.

Often it behaves to let the youngsters voice their point of views on the birthday celebration invites that they get. If they feel that something is a little odd after that it might be worth considering altering it. Obviously, it is additionally crucial to take into consideration the age of the child and his/her opinion on the issue. You do not want to distress your youngster and also still send kids celebration invites to the event.

Last but not least, do not overlook the crucial elements such as the color scheme, designs, as well as table placements when you are planning the event. Every one of these points will considerably impact the overall appeal of the celebration. There is absolutely nothing worse than having a great looking https://www.partyslate.com/event-pros/gigeo place, enhanced to an outstanding standard, however have a bad embellishing job. The children`s initial birthday event invitations must be sent in good taste, with some idea and consideration for their preferences. This should all be taken into consideration prior to sending the invites to the occasion.

What’s an IUL? Decoding Indexed Universal LifeWhat’s an IUL? Decoding Indexed Universal Life

Ever found yourself at a crossroads, trying to decipher the code of financial security and prosperity? Yes, we’ve all been there. Now, imagine stumbling upon a roadmap that not only promises to guide you but also introduces an intriguing concept: what’s an iul. Sounds like something out of a financier’s diary, Right?

This isn’t your everyday money talk. Far from it. Indexed Universal Life (IUL) insurance flirts with the boundary between daring investment and cautious savings plan. It’s Where the thrill of stock market indexes meets the steadfastness of life insurance.

The allure? A chance at higher returns without lying awake fearing market downturns. But here’s the kicker – those potential gains have limits. Yes, caps on how much you can earn might just be IUL’s way of saying “let’s keep this interesting.” And let’s not forget; it demands more than pocket change for its premium costs compared to simpler life policies.

Understanding Indexed Universal Life (IUL) Insurance

What Is an IUL Account?

Imagine a world where your life insurance does more than just offer peace of mind for the unexpected. Enter: indexed universal life (IUL) insurance. It’s not just any policy; it’s a savvy blend of protection and potential growth, wrapped up in one neat package.

How Does an IUL Account Work?

IUL policies are like the Swiss Army knife of the insurance world. Offering adjustable payments, these plans allow you to modify your contribution amounts within specified boundaries. But here’s where it gets interesting: part of your premium goes into accounts that can be tied to market indexes like the S&P 500 or Nasdaq-100. Think smart savings with a twist – while there’s a safety net ensuring you won’t lose cash when markets dip, there’s also a cap on how high your returns can go. And yes, this means sometimes dancing close to those caps when markets soar.

Is an IUL Account a Good Investment?

This is where opinions diverge faster than forks in fairy tales. Some say IULs shine brighter than traditional universal life policies, thanks to their earning potential tied to market performance—without directly exposing your hard-earned money to market risk. Others caution about capped gains and costs that might nibble away at what could have been yours outright had risks been taken elsewhere.

  • If retirement planning feels akin to navigating through fog without lights, adding an IUL could turn on some headlights.
  • If already maxing out other retirement avenues or seeking tax advantages offered by life insurance products.
  • If keen on leaving behind something substantial for loved ones while enjoying some financial perks along the way.

The truth? Whether an IUL account beams as brightly as Sirius in our night sky comes down mostly to personal circumstances and preferences – but getting acquainted with all its ins-and-outs is key before diving deep into its waters.

Key Takeaway: 


Think of an IUL as a smart combo of life insurance and potential market growth, with flexible premiums and safety nets. It’s perfect for those navigating retirement planning or wanting to leave something behind, but it’s essential to weigh its benefits against capped gains and costs.

The Benefits and Downsides of IUL Insurance

Pros: Indexed Universal Life Insurance

First up, the positives – who doesn’t love kicking things off on a bright note? Indexed Universal Life (IUL) insurance isn’t just another life insurance policy. It’s like the Swiss Army knife in your financial toolkit. Why?

  • Potential for higher returns: Unlike its cousin, traditional universal life policies, an IUL can give you a leg up with returns tied to market indexes. But don’t worry; there’s a safety net ensuring you won’t dive into negative territory when markets falter.
  • Tax-deferred growth on cash value: The IRS isn’t getting their hands on this till much later. That means more money compounding over time.
  • A sidekick for retirement planning: Imagine having a bucket of money that grows tax-free which you can dip into during retirement without triggering taxes or penalties? Yep, an IUL has got your back.
  • Lifelong coverage plus flexibility: Need to adjust how much you’re paying or what your beneficiaries get after you’ve moonwalked off this mortal coil? With an IUL, it’s no biggie.

Cons: Indexed Universal Life Insurance

No sugarcoating here – while IULs have their perks, they come with caveats too.

  • Capped gains mean limited fun: We love those years when the stock market is throwing a party because everyone’s portfolio gets fat… unless yours is capped because of your IUL policy terms.
  • You might need a PhD in patience and persistence: I’m kidding about the degree part but not about needing heaps of patience. Managing these policies takes work, keeping track so it doesn’t lapse due to underpayment.
  • Those pesky premium costs: Let’s be real—Quality comes at a price. While term life lets folks sleep easy knowing they’ve spent less, IUL asks for more upfront. And over time. That dough could potentially do better elsewhere, given half a chance.

There you go. The rundown on pros and cons. When considering if IUL is the right fit for you, weighing both sides is an essential step. So, make sure to grab a notepad and jot down how these factors align with your financial goals.

Key Takeaway: 


Think of IUL insurance as your financial Swiss Army knife: offering potential for higher returns, tax perks, and retirement help but watch out for caps on gains, the need for patience in management, and those premium costs.

Comparing IUL to Other Life Insurance Products

Indexed universal life insurance vs. term life insurance

Let’s kick things off with a classic face-off: IUL versus term life. The biggest difference? The crux of the matter lies in their longevity and the presence, or absence, of a monetary worth attached. Term life insurance is like renting an apartment – you’re covered for a set period, say 20 years, but when the lease is up, that’s it. No equity or cash value to show for it.

In contrast, indexed universal life (IUL) offers something more permanent. Think of it as buying a home – not only do you have lifelong coverage but there’s also potential to build cash value over time based on market indexes.

Indexed universal life insurance vs. whole life insurance

Moving onto the next contender: whole life insurance. This one’s got longevity in its corner too; providing lifetime coverage just like IULs do.

The main event here though? The way they handle your money. Whole-life policies are the steady Eddies offering guaranteed returns on your cash value component – slow and stable wins the race kind of vibe.

But if you’re feeling adventurous, an IUL throws in some spice by tying your earnings potential to stock market indexes without direct investment risk. It’s like having both safety nets and trampolines underfoot.

Indexed universal life insurance vs. variable life insurance

Last up we’ve got variable life insurance going head-to-head with our star player: IULs.

This showdown is all about control versus flexibility. Variable policies hand over the reins letting policyholders directly invest their cash values into stocks or bonds—big rewards if you know what you’re doing. On the flip side, IULs keep things a bit more reined in. Your cash value grows based on selected market indexes with caps and floors to protect you from wild market swings. So what’s our takeaway here? When picking between term life, whole life or variable policies versus an indexed universal one, it all boils down to how much risk you’re willing to take on for potential rewards and whether longevity of coverage is key for you.